When your home is damaged, figuring out what to do next can feel overwhelming. Many homeowners are unsure how long they have to report damage, what their insurance company needs, or whether a delayed claim may still have options.
Berger & Hicks, P.A. helps West Kendall homeowners understand their rights after denied, delayed, or underpaid property insurance claims.
Florida law places deadlines on when certain property insurance claims must be reported. Many homeowners still believe they have more time than the law allows, and waiting too long may give an insurer a reason to challenge or deny a claim. Storm damage, roof leaks, and water damage may become more difficult to pursue when important deadlines have passed.
Martin Berger and Zachary Hicks review property insurance disputes directly with homeowners to understand what happened, examine the available information, and explain possible next steps. Call (305) 670-7050 or fill out the contact form on this page to discuss your claim and learn where you stand.
Schedule Your ConsultationWhy West Kendall Homeowners Choose Berger & Hicks, P.A. For Property Insurance Claims
Property insurance disputes require more than reviewing a denial letter. They require attorneys who understand how insurers evaluate coverage decisions, document losses, and defend claim positions. Berger & Hicks, P.A. handles these disputes directly with homeowners, giving clients access to experienced attorneys instead of being passed between case managers or a large intake team.
Martin Berger brings 32 years of legal experience and an AV Preeminent rating to insurance disputes and personal injury matters. Zachary Hicks brings 21 years of experience and recognition from Super Lawyers.
Together, they help homeowners throughout West Kendall, Homestead, and South Miami-Dade address denied, delayed, and underpaid property insurance claims.
Direct Access To Experienced Attorneys
When homeowners contact Berger & Hicks, P.A., they work directly with Martin Berger or Zachary Hicks throughout the legal process.
The attorneys take time to understand what happened, review the available information, and explain the options available for challenging an insurer’s decision.
Experience Handling Complex Insurance Disputes
Property insurance claims often involve competing opinions about the cause of damage, the scope of repairs, and what the policy covers.
Berger & Hicks, P.A. uses decades of litigation experience to evaluate these disputes, prepare documentation, and address issues that arise when an insurer denies or undervalues a claim.
Spanish-Speaking Legal Support For South Miami-Dade Families
Berger & Hicks, P.A. provides legal guidance in English and Spanish. Spanish-speaking homeowners can discuss their property insurance concerns directly with the firm and better understand the claim process, available options, and next steps.
A Risk-Free Way To Review Your Claim
Homeowners do not have to decide how to move forward without first understanding their options. Berger & Hicks, P.A. offers free consultations, advances the costs of pursuing property insurance disputes, and charges no fee unless there is a recovery.
Whether your claim involves storm damage, water damage, roof repairs, or an insurer that denied or delayed payment, Berger & Hicks, P.A. helps homeowners understand what their policy covers and what steps may be available.
Call (305) 670-7050 or complete the contact form to schedule a free consultation with a property insurance attorney. There is no fee unless there is a recovery.
Schedule Your ConsultationWhat Qualifies As A Property Insurance Claim Dispute In Florida?
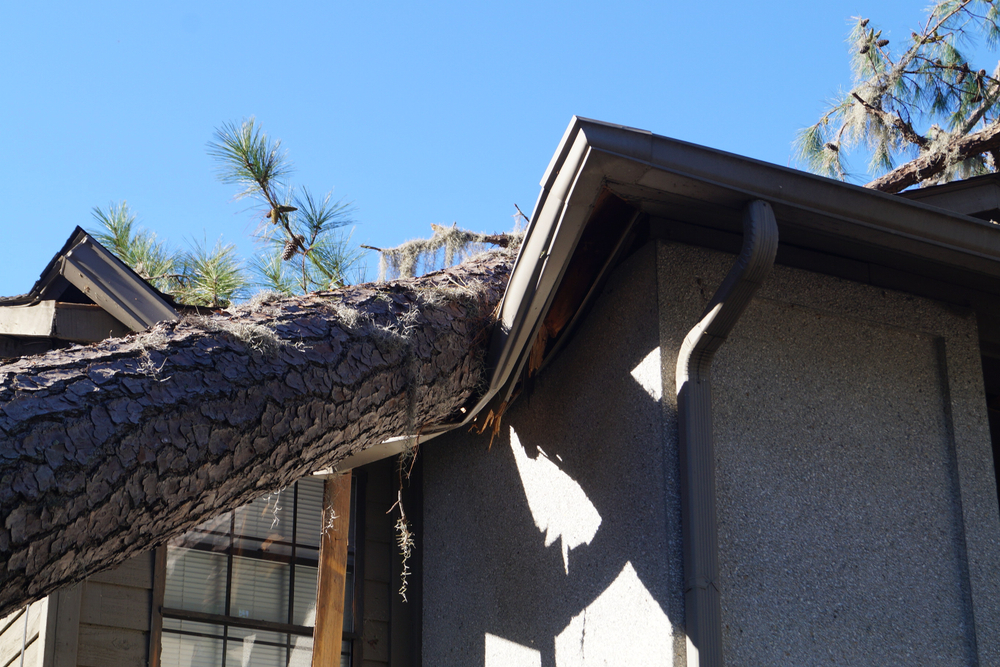
A property insurance claim dispute arises when an insurer denies, underpays, or unreasonably delays a claim for covered damage to a home or commercial property. Florida homeowners face these disputes after hurricanes, fires, water and plumbing failures, vandalism, theft, and sinkhole damage.
Every property policy requires the insurer to evaluate covered losses under the policy terms once the policyholder meets the reporting and documentation requirements.
Documenting the damage thoroughly from the start strengthens a claim before an insurer has any chance to dispute what happened.
- Photographs And Video: Images of the damage taken immediately, before repairs begin or debris gets cleared.
- Repair Estimates: Written estimates from licensed contractors detailing the scope and cost of repairs.
- Prior Inspection Records: Home inspection reports or maintenance records showing the property's condition before the loss.
- Communication Logs: Dates and notes from every call, email, and letter exchanged with the insurance company.
Gathering this evidence early removes an insurer's ability to argue later that damage existed before the loss or that repairs cost less than they actually do.
How Long Do You Have To Report Property Damage To Your Insurer In Florida?
Florida law sets specific deadlines for reporting property insurance claims, including different deadlines for initial claims, reopened claims, and supplemental claims under Florida Statute 627.70132. This deadline dropped from the previous two-year window following Florida's 2022 property insurance reform legislation.
Supplemental claims and reopened claims have separate reporting deadlines under Florida law based on when the claim was originally reported and when additional damage is identified. Missing a reporting deadline can create a significant challenge for a claim and may give an insurer grounds to dispute coverage.
This one-year clock applies broadly across property insurance claims.
- Hurricane And Windstorm Damage: Roof, siding, and structural damage caused by a named storm.
- Water And Plumbing Failures: Burst pipes, appliance leaks, and water intrusion from a failed roof or window seal.
- Fire Damage: Structural and contents damage caused by an accidental fire.
- Vandalism And Theft: Property damage or loss caused by a break-in or intentional act.
The deadline runs from the date the damage actually occurred, not the date a homeowner first notices it, which makes routine property inspections after any storm or water event a meaningful protection against missing this window entirely.
What Response Timelines Must Your Insurance Company Follow?
Florida law requires property insurers to respond to and process claims within specific deadlines under Florida Statute 627.70131. These timelines exist precisely because insurers previously took months to move claims forward while homeowners covered emergency repairs out of pocket.
Several concrete deadlines now govern how quickly an insurer must act.
- Initial Response: The insurer must acknowledge a claim communication within 7 days of receiving it.
- Investigation Start: The insurer must begin investigating the claim within 7 days after receiving a proof-of-loss statement.
- Physical Inspection: The insurer must conduct a physical inspection of the damage within 30 days.
- Payment Or Denial: The insurer must pay the full settlement, an undisputed portion, or deny the claim within 60 days, or interest starts accruing on the unpaid amount.
An insurer that blows through these deadlines without a documented reason opens itself up to interest penalties and gives a policyholder concrete evidence that the delay itself violated the claims handling process.
Why Do Property Insurance Companies Deny Or Underpay Claims?
Property insurance companies deny or underpay claims using a consistent set of arguments designed to reduce their payout regardless of the actual damage. Big Insurance carriers train adjusters to spot any gap between the policy language and the homeowner's documentation.
Certain denial and underpayment tactics appear across nearly every disputed property claim.
- Disputing The Cause Of Loss: Arguing the damage came from wear and tear or lack of maintenance rather than a covered peril.
- Alleging Pre-Existing Damage: Claiming photographs or inspection reports show damage that predates the reported loss.
- Issuing A Lowball Estimate: Sending an adjuster's estimate far below what licensed contractors quote for the same repairs.
- Citing Late Notice: Denying the claim outright based on the one-year reporting deadline, even when the delay was reasonable.
Recognizing which tactic an insurer used shapes the entire approach to challenging the denial, since each argument requires different evidence to overcome.
What Happens If Your Property Insurer Acts In Bad Faith?
A Florida property insurer can face a bad faith claim when it fails to act in good faith in handling a claim as required under Florida Statute 624.155.
Since Florida's 2022 reform, property insurance bad faith claims are subject to additional statutory requirements, including requirements related to establishing the insurer's liability for coverage.
This sequencing matters. A homeowner generally needs to win the underlying breach of contract claim before pursuing a separate bad faith action against the same insurer.
Several patterns tend to support a bad faith claim once the breach itself has been established.
- Unreasonable Delay: Stretching the claims process well beyond the statutory response deadlines without justification.
- Unsupported Lowball Offers: Offering a settlement with no documented basis in an independent damage assessment.
- Ignoring Contractor Evidence: Disregarding repair estimates and reports submitted by the homeowner's own contractors.
- Failure To Investigate Properly: Skipping the required physical inspection or proof-of-loss review altogether.
A pattern of this conduct, documented from the earliest communications with the insurer, becomes the foundation of a bad faith claim once the contract dispute itself gets resolved.
How Does Filing A Property Insurance Lawsuit Work In Florida?
Filing a property insurance lawsuit in Florida generally starts with a presuit notice to the insurer under Florida Statute 627.70152, before filing suit. The requirements and timing depend on the type of claim and applicable law. Homeowners then have five years from the date of loss to file a breach of contract lawsuit under Florida Statute 95.11(2)(e).
Martin Berger brings 32 years of trial experience and an AV Preeminent rating to property insurance disputes, and Zachary Hicks brings 21 years of experience and a Super Lawyers recognition.
Both attorneys work on these disputes directly with clients throughout West Kendall, Homestead, and the South Miami suburbs, coordinating the presuit notice, documentation, and any resulting litigation in English or Spanish.
A homeowner facing a denied or underpaid claim benefits from an accurate account of every deadline that already applies to their specific loss, since the one-year notice deadline, the insurer's response timelines, and the five-year litigation window all interact differently depending on when the damage occurred.
FAQs For West Kendall Property Insurance Lawyers
My insurance company denied my claim saying I reported it too late. Can I still do anything?
Maybe, depending on when the damage actually occurred and when you first reported it. Florida's one-year notice deadline is strict, but the exact date of loss and the reporting date both need review before assuming the claim is permanently barred.
The adjuster's estimate is way lower than what my contractor quoted. What are my options?
You may challenge the adjuster's estimate by submitting your contractor's documentation and requesting a reevaluation or appraisal under your policy. A significant gap between the two estimates often signals the insurer's number was not based on an accurate inspection.
Do I need to hire a public adjuster before contacting a lawyer?
No, you do not need a public adjuster before speaking with an attorney about a denied or underpaid claim. Some homeowners use both, but an attorney addresses the legal deadlines and dispute process a public adjuster cannot handle alone.
What if my insurance company keeps asking for more documents and delaying my payment?
This may constitute an unreasonable delay if it stretches beyond Florida's statutory response deadlines under Section 627.70131. Documenting every request and every date helps establish whether the delay crossed into bad faith territory.
Can I still file a claim if my roof damage happened over a year ago?
No, generally not, since Florida's one-year notice deadline under Section 627.70132 bars most claims reported after that window closes. Certain narrow exceptions exist for hidden damage that could not reasonably have been discovered sooner.
Does filing a lawsuit against my insurer cost me anything upfront?
No, Berger & Hicks, P.A. advances the costs of pursuing a property insurance dispute and charges no fee unless the client recovers. A free consultation reviews the specific facts of your denial before any commitment is made.
Can I sue my insurance company directly, or do I have to go through arbitration first?
It depends on your specific policy, since some Florida property policies now include a binding arbitration clause under Section 627.70154. Reviewing your policy's dispute resolution section determines whether arbitration applies before a lawsuit becomes an option.
What if my insurance company denies my claim based on a policy exclusion I didn't know about?
Yes, you may still challenge a denial based on a policy exclusion, particularly if the exclusion's language is ambiguous or was not properly disclosed. Florida courts interpret ambiguous policy language in favor of the policyholder in many circumstances.
Is there a difference between how Florida handles hurricane damage claims versus water damage claims?
Not for the reporting deadline itself, since the one-year notice requirement under Section 627.70132 now applies to any covered peril rather than just hurricanes. The type of damage does affect what documentation and inspection process best supports the claim.
Get An Honest Read On Your Denied Property Claim
A denial letter reads like a final answer, but Florida law gives homeowners real tools to challenge an insurer's math when the numbers do not add up. Martin Berger and Zachary Hicks review these letters directly against the policy language and the documented damage.
Call Berger & Hicks, P.A. at (305) 670-7050, submit the contact form on this page, or visit the firm at 9700 South Dixie Highway, Suite 850, Miami, FL 33156 to go over what your insurer actually owes you.
Schedule Your Consultation